Lagging the trading position by one day removed information that was unavailable at execution time.
QUANTITATIVE RESEARCH · TRADING · MODEL VALIDATION
I turn market questions into testable, auditable research.
I build and test market models in Python, with explicit controls for bias, leakage, transaction costs, and out-of-sample performance.
forecast.py · validated
# leakage-aware time-series evaluation
train, test = chronological_split(data)
train = purge_boundary(train, horizon=21)

# identical held-out dates
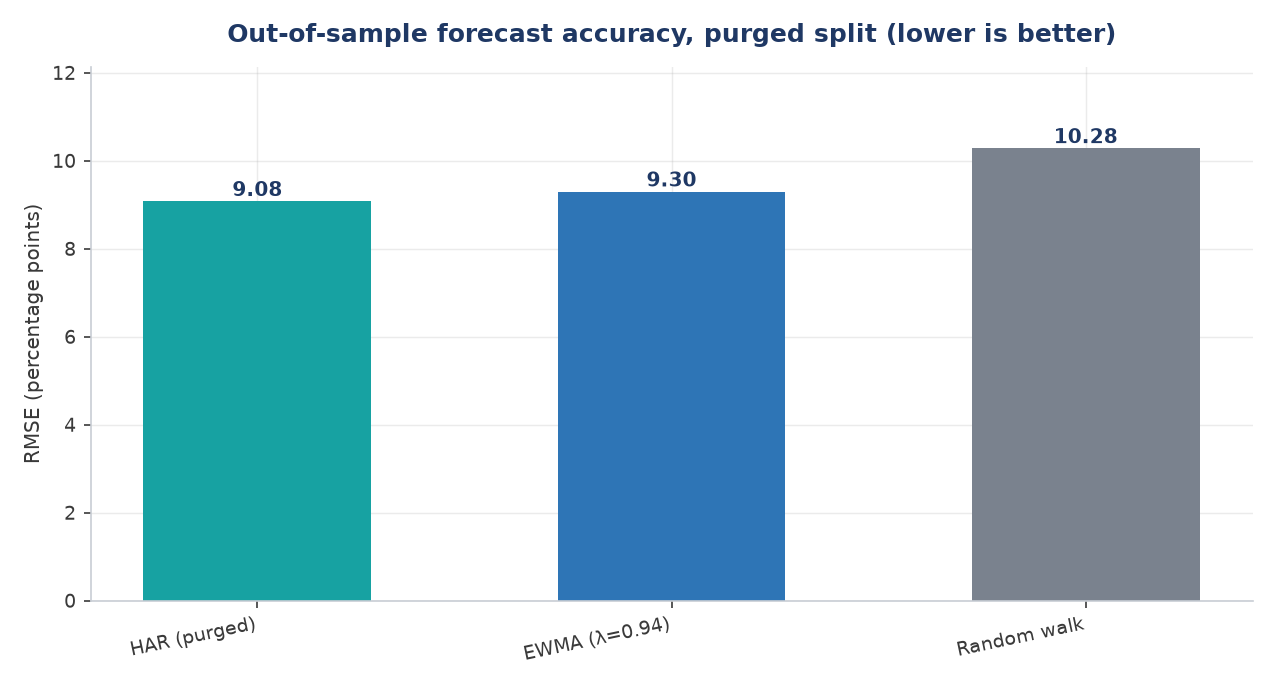
rmse(har, target)   9.08%
rmse(ewma, target)  9.30%
rmse(random_walk) 10.28%STATUS15 / 15 integrity checks passing
9.08%purged HAR RMSE
15 / 15integrity tests passing
2007–2016four-equity sample
2.34%HAR improvement vs EWMA
01 / FLAGSHIP RESEARCH
PYTHON · PANDAS · NUMPY · TIME SERIES · SUPERVISED LEARNING
Equity Volatility Research Pipeline
An end-to-end investigation that moved from return construction and strategy backtesting to volatility diagnostics and leakage-aware forecasting.
Open the case studyOUT-OF-SAMPLE RESULT
HAR remained strongest after purged validation.
Purging 21 boundary observations raised HAR RMSE from 9.03% to 9.08%. The lower unpurged figure is preserved as a diagnostic; the corrected result is the headline.
1,563 training21 purged679 test
The net SMA strategy beat buy-and-hold on none of the four equities tested—an informative null result.
Changing only the evaluation target reversed the apparent forecast ranking and exposed a misleading overlap.
02 / PROFESSIONAL QUANTITATIVE & MARKETS EXPERIENCE
Model monitoring and financial systems backed by auditable controls.
My current work spans HAR volatility-model monitoring across 512 forecast origins, Python/pytest validation of multi-currency FX settlement, compliance-risk testing, and commodity-pricing and financial-data analysis across a $4.91 million portfolio.
Explore professional experience512forecast origins monitored
96 / 96gold-standard rubric score
6 / 6FX scenarios matched
$4.91Mfinancial portfolio analyzed
03 / SELECTED WORK
Quantitative research, trading systems, and production evidence.
The flagship market study is supported by work in trade controls, data validation, software engineering, and peer-reviewed research.
01
QUANTITATIVE RESEARCH · FLAGSHIP
Equity Volatility Research Pipeline
Strategy backtesting, volatility persistence, target design, and HAR forecasting under a purged out-of-sample protocol.
15 integrity tests · 9.08% HAR RMSE02
TRADING OPERATIONS
Trading Operations Monitor
A Python control framework for trade states, positions, P&L, market-data health, reconciliation, and exception triage.
60 trades · 10 deliberate exceptions03
PRODUCTION SYSTEM
JobX.OS
A full-stack AI platform presented through the same disciplines that matter in quant systems: measurement, validation, data integrity, and controlled releases.
2,000+ users · 99.9% uptime04
CAUSAL INFERENCE · PEER-REVIEWED
Causal Inference & Genomic Research
First-author Wiley research covering instrumental variables, robustness estimators, bias mechanisms, and measurement trade-offs.
Wiley · Top Viewed Article 2025
ABOUT THE RESEARCHER
Engineering, quantitative economics, and research judgment.
Rutgers graduate with a B.S. in Mechanical Engineering, a minor in Quantitative Economics, a 3.84 GPA, and Summa Cum Laude honors. I combine first-principles modeling, causal-inference research, production data controls, and hands-on Python research.
Read the full profileQUANTITATIVE RESEARCH · TRADING · DEVELOPMENT